
One of the most valuable gifts you can give your children is the gift of financial security, which begins with strong financial habits.
Teaching kids to manage money: Age-by-age actions
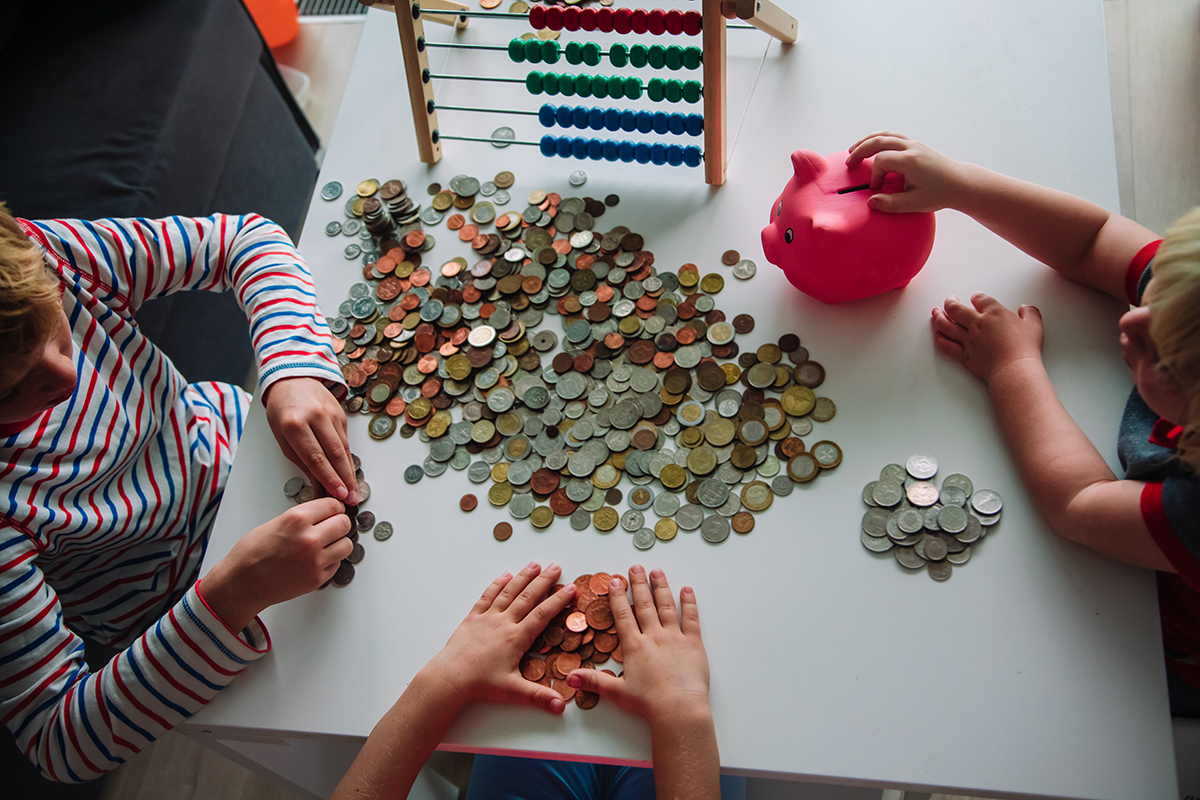
One of the most valuable gifts you can give your children is the gift of financial security, which begins with strong financial habits.
One of the most valuable gifts you can give your children is the gift of financial security, which begins with strong financial habits. Some studies suggest that money habits are established as early as age 7, which means that the sooner you start teaching your kids how to manage their money, the better off they may be1.
Consider starting simple with age-appropriate financial lessons that help your children develop a healthy approach to financial management. Here is an age-by-age guide to engaging activities that can help your children establish a positive relationship with money.
Young children are curious about the world and thrive on interaction with trusted adults, which makes this a great age to start teaching them about money as a concrete concept. Focus on helping them recognize money, demonstrate the basics of exchanging money for items they desire and teach them that money is limited. This is also a great age to start working on basic math concepts, such as greater than/less than, sorting, counting and comparing.
Some ideas of games and lessons at this age include:
Tip: Keep things playful and fun so your child will want to continue engaging with your money lessons.
Children in this age range understand cause and effect, which makes this a great age to introduce the concepts of earning through effort and delayed gratification.
Tip: Let your child make mistakes. For example, resist the urge to step in if your child decides to spend all of his/her savings at once rather than saving it for a special purchase. Mistakes and regrets are often the most powerful teachers.
At this age, children are ready for more independence and can better prioritize their decision making. It’s a great age to help them strengthen their long-term priorities.
Tip: Involve your child in family budgeting discussions and give him/her a say in certain decisions. For example, discuss as a family how much you plan to spend on a summer vacation.
This is a great age to shift from directing to coaching, as teens are ready to take on more financial responsibility.
Tip: The goal at this age is to give your child freedom with guardrails. For example, establish accounts your child can manage, but be sure to check in regularly and offer guidance as needed.
At this age, children are preparing for adulthood, so it’s important to start letting go of the reins.
Tip: Start coaching your child on real-world scenarios. For example, share how you handle budgeting, saving and investing. Also discuss the cost of real-world expenses, such as rent, food and insurance.
As you teach your child about money, remember that consistency is key. Engage in regular conversations over time, rather than one big talk with little follow up. Also, it’s important to lead by example, but it’s also okay to make mistakes. Talk about your money mishaps and share the lessons you’ve learned along the way. By maintaining an open, honest dialogue throughout the years, you can teach your kids real-world financial lessons that will stay with them throughout life.
Sources:
This material is provided for informational and educational purposes only. It does not consider any individual or personal financial, legal, or tax circumstances. As such, the information contained herein is not intended and should not be construed as individualized advice or recommendation of any kind. Where specific advice is necessary or appropriate, individuals should contact their professional tax, legal, and investment advisors or other professionals regarding their circumstances and needs.
There is no assurance that any investment, plan, or strategy will be successful. Investing involves risk, including the possible loss of principal. Past performance does not guarantee future results, and nothing herein should be interpreted as an indication of future performance.
Mariner is the marketing name for the financial services businesses of Mariner Wealth Advisors, LLC and its subsidiaries. Investment advisory services are provided through the brands Mariner Wealth, Mariner Independent, Mariner Institutional, Mariner Ultra, and Mariner Workplace, each of which is a business name of the registered investment advisory entities of Mariner. For additional information about each of the registered investment advisory entities of Mariner, including fees and services, please contact Mariner or refer to each entity’s Form ADV Part 2A, which is available on the Investment Adviser Public Disclosure website. Registration of an investment adviser does not imply a certain level of skill or training.